A commercial loan can solve an immediate funding problem, but the exit is what gives a lender confidence to fund it. Strong commercial loan exit strategies show how borrowed funds will be repaid within the agreed term, whether that is through a property sale, refinance, settlement of another transaction or business cash flow. For private and short-term commercial finance, the proposed exit can be as important as the security itself.
A borrower may have substantial equity in a commercial site, development land or retained stock, yet still face difficulty if the repayment pathway is vague. Conversely, a clear and well-supported exit can help a lender assess risk, structure the term properly and move quickly when timing matters.
Why the Exit Strategy Matters to Commercial Lenders
Commercial lenders do not simply assess whether a property has enough value to secure the loan. They also need to see how the debt will be cleared. This is particularly relevant for bridging finance, caveat loans, second mortgages, development funding and other facilities designed to address a defined short-term need.
An exit strategy answers practical questions: What event will generate repayment funds? How likely is that event to occur within the loan term? What could delay it? And does the borrower have enough time and contingency to manage those delays?
For example, a developer seeking funds to complete head works may intend to refinance into a construction or residual-stock facility once practical completion is achieved. That can be a credible pathway, but only if the valuation, remaining works, projected end values and refinance parameters support it. A statement that the project will “be refinanced later” is not enough on its own.
The best exit plans are specific, evidenced and aligned with the purpose of the facility. They do not need to be complicated. They do need to make commercial sense.
The Most Common Commercial Loan Exit Strategies
Sale of the secured property or asset
Selling a property is a common exit for site acquisitions, bridging loans, incomplete developments and loans secured against surplus or non-core real estate. Lenders will generally look beyond an optimistic agent appraisal. They may consider an independent valuation, local sales evidence, current listings, the expected sale period and any costs that reduce net proceeds.
For development stock, timing is often the pressure point. A lender may be comfortable with a sale-based exit where completed units are marketable and there is adequate equity, but less comfortable where settlement depends on FIRB approval, title registration, unresolved defects or a thin buyer market.
A sale exit should allow for selling costs, interest, legal costs and a realistic buffer. If the loan relies on achieving the very top end of the valuation range, it may need a stronger alternative exit.
Refinance to a bank or non-bank lender
Refinance is often the preferred exit where a borrower uses private funding to act quickly, settle a purchase, clear an urgent liability or complete a value-adding project before moving to longer-term finance. It can be a sensible structure, especially where the current position does not meet mainstream bank policy but is expected to improve.
The key question is whether the borrower will meet the next lender’s requirements when the private loan matures. That may depend on completed construction, stabilised rental income, improved credit conduct, lodged financials, reduced debt or finalised leases.
A refinance exit is more credible when there is evidence of likely eligibility. This could include a broker assessment, serviceability calculations, an anticipated valuation, tax returns, management accounts or a conditional indication from a suitable lender. It is also wise to allow for conservative loan-to-value ratios. A future valuation may not match the current expectation, particularly in specialised property or regional markets.
Sale of retained stock or project settlements
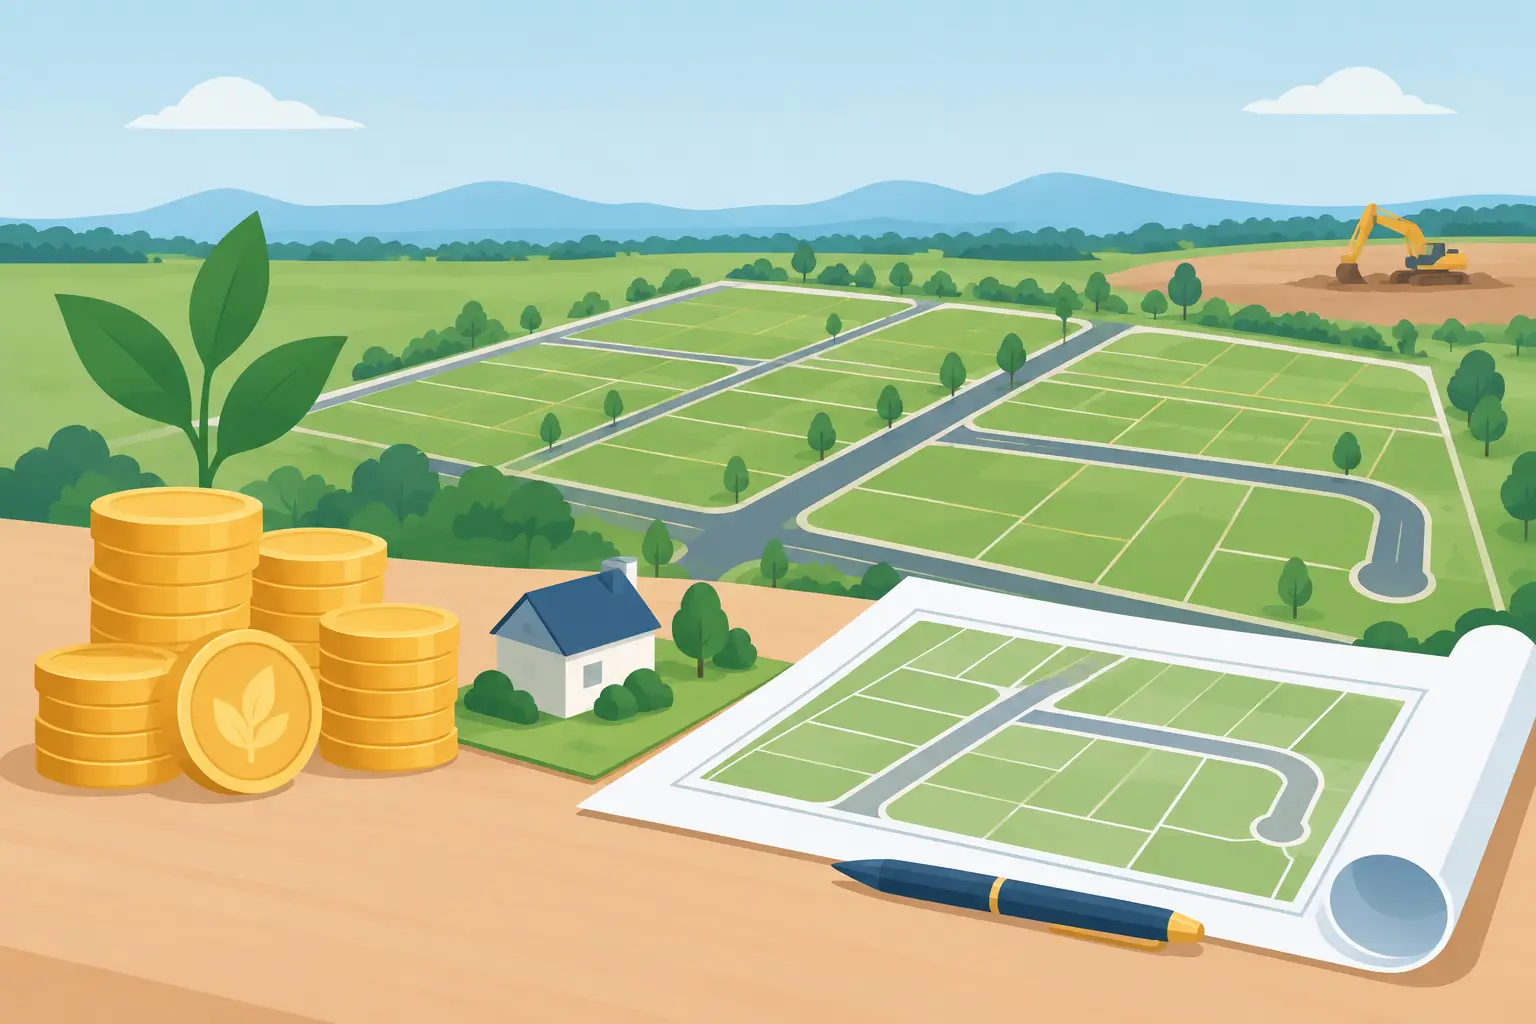
For developers, unit or townhouse settlements can provide a direct and logical repayment source. This is common where funding is required to finish construction, release titles, complete civil works or carry remaining stock after presales have settled.
Lenders will look closely at the settlement schedule, deposit status, purchaser conditions and whether any contracts are subject to finance or FIRB approval. They may also assess how many sales are required to clear the facility and whether unsold stock provides a workable fallback.
Where a project has only a small number of remaining lots, a retained-stock loan may be structured around a defined sales program. Where sales are slower, a refinance against completed stock may be the more appropriate secondary exit.
Business cash flow or asset realisation
Some commercial loans are repaid from operating cash flow, particularly working-capital facilities, equipment finance and debt consolidation. This can work well for established businesses with predictable revenue, healthy gross margins and clear evidence that the funding will improve the trading position.
A business owner may use a short-term property-secured loan to purchase inventory before a contracted sales period, pay an ATO obligation, consolidate expensive debt or cover a temporary gap caused by delayed invoices. In each case, the lender will want to understand the cash conversion cycle rather than rely on a broad expectation that turnover will increase.
For an asset-backed exit, evidence could include a sale contract, order book, invoice ledger, asset valuation or auction plan. The asset must be readily saleable and the likely net proceeds need to be sufficient after any prior-ranking finance is paid out.
How to Make an Exit Strategy More Credible
A lender does not expect every future event to be guaranteed. Property sales can take longer than expected, valuations can change and bank credit teams can impose new conditions. What lenders want is a realistic primary exit, supported by facts, plus a sensible Plan B.
For a refinance exit, show the expected loan balance at maturity, estimated property value, likely loan-to-value ratio and the borrower income or business position that supports the proposed replacement facility. For a sale exit, provide a conservative sales estimate, agent feedback, campaign timing and a calculation of net funds after costs.
It also helps to explain what will change during the loan term. If the loan funds completion of a warehouse fit-out, the exit case may improve because a tenant is ready to occupy the property. If the funds clear mortgage arrears and business debt, the borrower may be able to demonstrate cleaner repayment conduct before refinancing. If the facility completes a development, practical completion and individual titles may create a broader range of lender and buyer options.
Documentation matters. Depending on the scenario, a lender may request valuations, contracts of sale, development approvals, quantity surveyor reports, build contracts, council information, financial statements, BAS records, rent rolls, tenancy agreements or payout letters for existing debt. Providing these early can reduce back-and-forth and help lenders assess the deal on its actual merits.
Match the Loan Term to the Exit Timeline
One of the most common mistakes is choosing the shortest possible term because the rate appears lower, then discovering the exit needs more time. A six-month facility may suit a settled sale contract or a straightforward refinance already in progress. It may be too tight for a development completion, subdivision, title registration and sales campaign.
A longer term can cost more in interest or establishment fees, but it may offer better risk management if the exit has several moving parts. The right choice depends on the strength of the security, the urgency of the funds, the reliability of the proposed repayment source and whether the lender permits early repayment without excessive cost.
Borrowers should also consider whether interest is paid monthly, prepaid, capitalised or retained from the loan proceeds. Retained interest can preserve cash flow during a project, but it reduces available funds and must be factored into the total payout figure.
When a Second Exit Is Essential
A secondary exit is particularly valuable where the primary plan relies on a third party. A buyer may delay settlement. A bank may change policy. A purchaser may not obtain finance. A developer may face weather delays, variations or a slower-than-expected sales rate.
A practical backup might be refinancing completed stock if individual sales are delayed, selling one additional asset, injecting equity, or extending the facility where the lender is comfortable with progress and security value. It should be achievable, not merely theoretical.
For complex transactions, No Doc Loans can assess the intended use of funds, available security and proposed repayment pathway before matching the scenario with suitable private lenders. The aim is not simply to obtain funds quickly, but to structure a facility that gives the borrower sufficient room to execute the exit.
Before committing to commercial finance, test the exit with conservative numbers. If the sale price is lower, the valuation is tighter or settlement takes longer, can the loan still be repaid? A clear answer to that question puts you in a stronger position to secure funding and keep control of the transaction.

Leave A Comment