
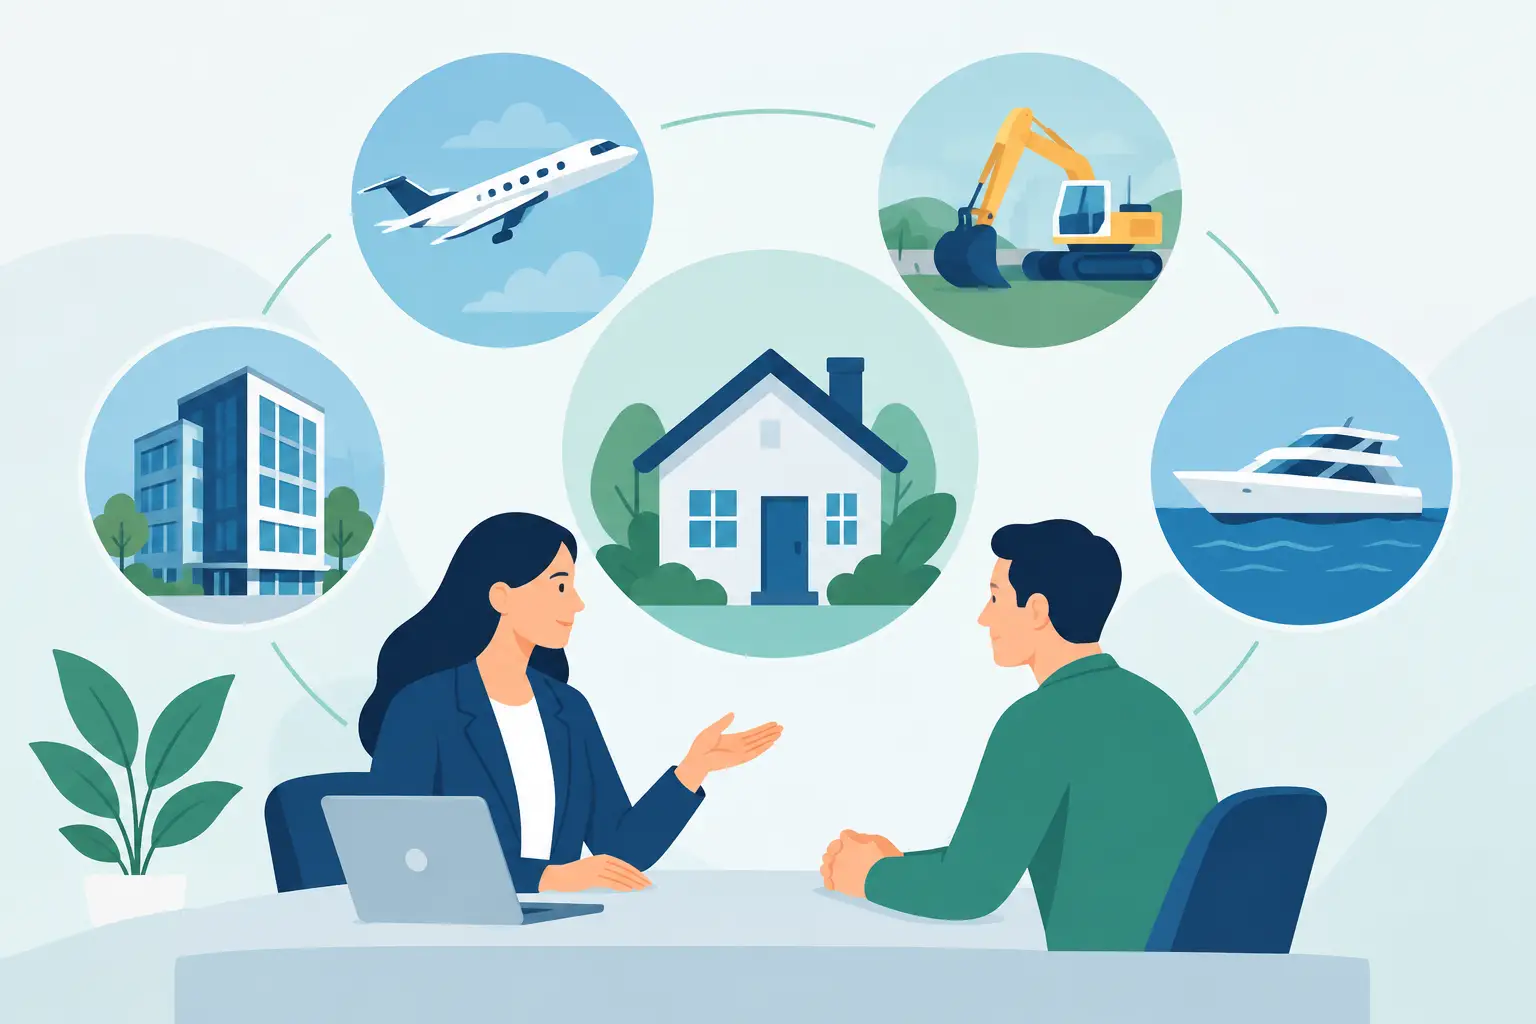
A settlement date, overdue BAS liability or construction payment does not wait for a bank credit team to finish another round of questions. So, can companies borrow against property? Yes. An Australian company can obtain business-purpose finance secured by residential, commercial, industrial or development property, provided the security, equity and proposed exit make sense to the lender.
The property may be owned by the borrowing company itself, a related trust, a director, or another party prepared to provide security. That flexibility is often what makes private lending relevant when a conventional bank is moving slowly, has declined an application, or requires financials that do not reflect the commercial reality of the deal.
How companies borrow against property
Property-backed company finance is not limited to buying a building. The lender takes security over real estate, usually through a registered first mortgage, second mortgage or caveat, while the company receives funds for a business purpose. The loan may be advanced as a lump sum, a staged development facility, a line of credit or a short-term bridging facility.
A first mortgage sits at the front of the security queue. It is generally used where there is no existing debt to refinance, or where the new lender is paying out the current first mortgage. A second mortgage sits behind an existing first mortgage and uses the remaining equity. It can be a practical solution where an established lender will not increase its facility but there is sufficient value in the property.
A caveat loan is generally shorter term and can be arranged against property equity where speed is critical. It does not replace a full assessment of the transaction, but it can suit a business needing funds for a time-sensitive opportunity, tax obligation, wages, stock purchase or settlement. The right structure depends on the available equity, existing encumbrances, time frame and credible repayment strategy.
When can companies borrow against property?
Lenders are primarily looking for a commercially clear transaction. A profitable trading history helps, but it is not the only path to approval in private credit. A company with uneven income, historic credit issues or a newly formed special-purpose vehicle may still have options where the property security and exit are strong.
In practice, a lender will assess the property value, the amount already owing against it, the borrower and guarantor position, the purpose of the funds, and how the loan will be repaid. That repayment may come from a sale, refinance, completed project settlements, retained stock sales, business cash flow or a planned asset disposal.
For a company borrowing against a director’s home or investment property, directors commonly provide personal guarantees and the property owner signs the relevant security documents. If a family trust owns the security, the trustee and beneficiaries may also need to be considered. These arrangements need to be documented correctly. The fact that a related party owns the property does not prevent funding, but it does change the parties involved and the approvals required.
Common company funding scenarios
Property equity can support a wide range of business purposes. The strongest applications explain exactly why the funds are needed and how that use supports the exit.
A commercial operator may refinance expensive short-term debt into a more manageable facility. A developer may use a second mortgage to complete head works, fund construction overruns or hold residual stock while sales are finalised. A business may bridge the purchase of premises before another property settles. An importer, manufacturer or retailer may need working capital to buy stock for a confirmed sales period.
Other common uses include paying ATO liabilities, covering wages, purchasing equipment, funding an acquisition, buying a development site, meeting a settlement shortfall, or consolidating multiple business debts. Asset finance may be more suitable where the main requirement is plant, vehicles or machinery. Where property equity is available, it can sometimes sit alongside asset finance to create a more workable capital structure.
How much can a company borrow?
The headline figure is usually driven by loan-to-value ratio, or LVR. If a property is worth $2 million and has a $900,000 first mortgage, there may be equity available for additional funding. But a lender will not simply lend the difference between the property value and existing debt. It will apply its own LVR limit, valuation approach, interest and fee allowances, and assessment of the exit.
The acceptable LVR varies by property type and risk. A well-located metropolitan house with a clear title may support a higher LVR than a specialised regional commercial property, a partly completed development or land without an immediate development approval. Vacant land, rural assets, company-owned premises and properties with unusual tenancy arrangements can all be financeable, but generally require a more considered lender match.
For development transactions, the assessment can be more detailed. Lenders may examine planning status, build contract, quantity surveyor reports, presales, construction progress, end values and the developer’s experience. Lack of presales does not automatically end the conversation, particularly where the site has a strong equity position and a sensible exit. It does, however, affect pricing, leverage and the lender pool.
What documents will lenders want?
Private lenders can move faster than banks, but fast finance still depends on having the right information ready. A simple refinance against a standard residential property may need relatively limited documentation. A development, business acquisition or second mortgage will require more detail.
At a minimum, expect to provide the company details, director identification, current rates notice, mortgage statement if applicable, and a clear outline of the funding purpose. Lenders will also want an estimate of the property’s value and an explanation of repayment. Depending on the transaction, they may request financial statements, BAS, bank statements, a contract of sale, development approval, plans, construction costings, valuation reports or evidence of expected sale proceeds.
Be direct about credit impairments, ATO debt, existing defaults or delays in a project. These issues are not necessarily deal breakers, but surprises late in the process can cost time and reduce certainty. A lender can price and structure around a known issue more effectively than one discovered after terms have been issued.
The trade-offs of property-backed private finance
Using property as security can give a company access to capital that unsecured business lending cannot provide. It can also be faster and more flexible where the funding requirement is short term, asset-backed or outside bank policy. That does not make it the right answer for every business.
Private property loans can carry higher interest rates and fees than mainstream bank facilities, particularly for second mortgages, caveat loans and complex development funding. Terms are often shorter, so the exit must be realistic rather than hopeful. If a proposed refinance depends on a major improvement in revenue, a future valuation uplift or property sales that have not yet commenced, the lender will look closely at the contingency plan.
Directors should also understand the consequences of providing personal guarantees or offering personally held property as security. The company may be the borrower, but the security provider’s asset is at risk if the loan is not repaid. Independent legal, financial and tax advice is worthwhile before signing documents, especially where trusts, multiple entities or related-party security are involved.
Choosing the right loan structure
The cheapest-looking rate is not always the most useful facility. A business buying stock may need rapid drawdown and a repayment profile aligned with its trading cycle. A developer with an incomplete project may need staged advances and a lender comfortable with residual stock. A company refinancing a looming default may need a short-term bridge that gives it time to sell or move to a lower-cost lender.
This is where lender selection matters. Different lenders have different appetites for second mortgages, regional property, impaired credit, construction completion, commercial assets and trust or company structures. Presenting the deal to a lender that regularly funds that scenario can improve both speed and the quality of the terms offered.
No Doc Loans works with a broad panel of private lenders to assess the property, funding requirement and exit strategy, then seek suitable options for business-purpose borrowers. The most productive first step is to have a clear loan amount, property details, existing debt position and intended repayment path ready for an obligation-free discussion. A well-presented application gives lenders a reason to move, which is often exactly what a time-critical business transaction needs.

Leave A Comment