A profitable business can still look difficult on a bank application. If your income moves between projects, sits in a trust, is reinvested in stock or depends on contract milestones, standard servicing models may not reflect your actual position. The best non-standard lending solutions for self-employed borrowers in Australia look beyond a single payslip or two years of clean tax returns. They assess the purpose of the funds, available security, equity and, critically, a credible exit strategy.
For business owners, developers and commercial property investors, non-standard finance is not simply a fallback after a bank decline. Used well, it can provide the capital to settle an acquisition, finish a project, release equity or manage a short-term cash requirement while a longer-term funding outcome is arranged.
Why self-employed borrowers fall outside bank policy
Mainstream lenders prefer consistency. They commonly want lodged financials, tax returns, business activity statements, stable income over several years and straightforward company structures. That can be workable for an established operator with predictable earnings. It becomes restrictive when revenue has recently grown, income is retained in the business, a new contract has changed turnover, or a development is between construction and sales.
A bank may also take time to assess exceptions. For a borrower facing a settlement date, ATO payment arrangement, construction completion deadline or opportunity to purchase discounted stock, timing can be as important as rate. Non-standard lenders tend to focus more closely on asset security, loan-to-value ratio, transaction purpose and the practical pathway for repaying the loan.
That does not mean documentation never matters. Better information generally supports stronger pricing and more lender options. The difference is that a private lender may be prepared to work with management accounts, BAS statements, bank statements, contract evidence or a clear project feasibility where a traditional lender requires a more prescriptive file.
Best non-standard lending solutions for self-employed borrowers
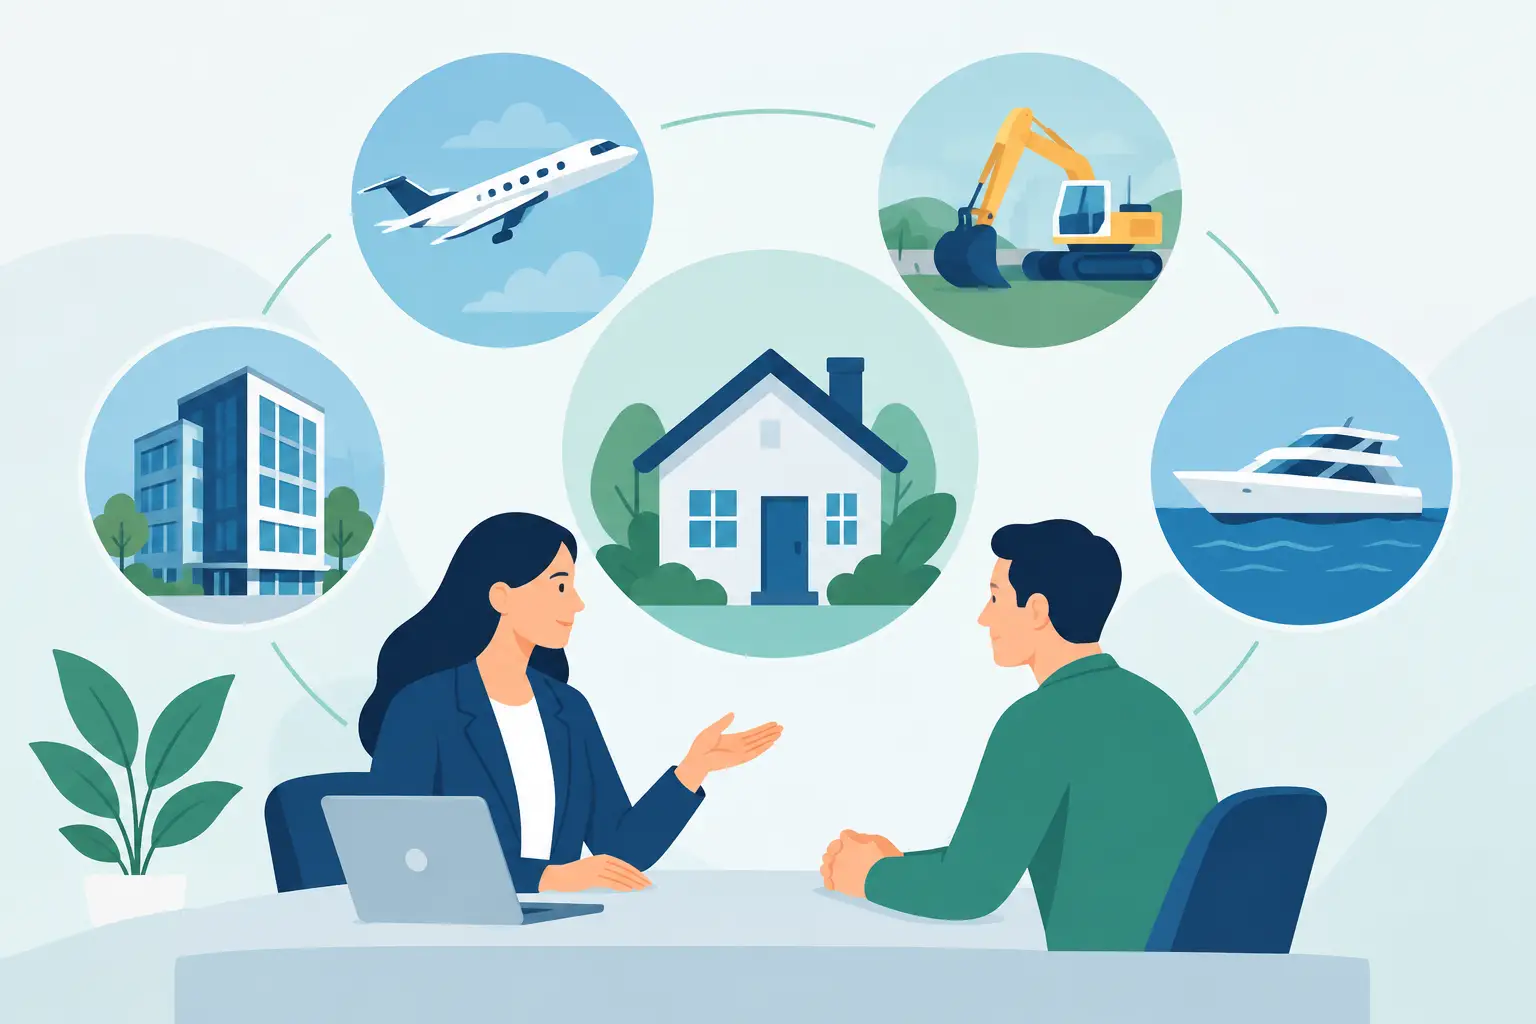
The right facility depends on what needs to be funded, the security available and how long the money is required. A short bridge for a property settlement should not be structured like a multi-year equipment purchase, and a developer completing retained stock needs a different capital solution to a business owner buying a commercial premises.
Private first mortgage loans
A private first mortgage is often the most practical option where a borrower owns, or is acquiring, residential, commercial or industrial property and needs business-purpose funding quickly. The property secures the loan in first position, giving the lender a clear security interest and allowing the assessment to centre on available equity and the exit.
Typical uses include purchasing a commercial site, refinancing an existing private loan, funding a site acquisition, completing head works, releasing capital for a business acquisition or consolidating business debts. These facilities can suit company and trust borrowers, including those with complex income, recent credit issues or a requirement to settle before a bank can complete its process.
The trade-off is cost. Private first mortgage finance is usually priced above mainstream bank debt and is commonly designed as short- to medium-term funding. Borrowers need to be realistic about interest, establishment costs, valuation requirements and the repayment plan, whether that is property sale, refinance, business cash flow or an expected settlement.
Caveat loans for urgent working capital
A caveat loan may suit a business owner who has substantial equity in property but needs a relatively smaller amount quickly. Instead of registering a mortgage, the lender lodges a caveat on title to protect its interest. This can make the process faster and less document-heavy than a conventional mortgage, particularly where the loan is required for a defined commercial purpose.
Caveat finance is commonly used for wages, supplier payments, tax liabilities, stock purchases, legal settlements and bridging a cash-flow gap before an invoice, sale or refinance completes. It can also be useful when a first mortgage already exists and there is adequate equity behind it.
Speed should not be confused with cheap money. Caveat loans are generally short term and can carry higher rates and fees. They work best when the repayment event is identifiable and close, rather than as a permanent answer to an ongoing cash-flow shortfall.
Second mortgages and equity release
A second mortgage allows a borrower to raise funds behind an existing first mortgage. It can be a useful solution when the first lender will not increase its facility, refinancing the first mortgage would be inefficient, or the borrower needs to preserve a favourable senior loan.
For self-employed operators, a second mortgage can fund expansion, development costs, debt consolidation, an equity contribution to a purchase or a time-sensitive opportunity. The key question is the combined loan-to-value ratio. The second mortgage lender must be comfortable with the first mortgage balance, the property value, the proposed loan amount and the likely timing of the exit.
Because second-ranking security carries more risk, pricing and lender conditions will normally reflect that. A clear plan to refinance, sell an asset or repay from a defined business event is essential. It is not a structure to enter without understanding exactly how the senior debt and second debt will be cleared.
Development and construction completion funding
Developers regularly encounter a funding gap after a builder variation, delayed presales, valuation movement or a cost overrun. Conventional construction lenders can be reluctant to step in mid-project, particularly where there are incomplete works, residual stock or presale requirements that no longer fit policy.
Private development funding can be structured against the land and project, with funds directed towards construction completion, civil works, head works, marketing, interest capitalisation or refinancing an existing facility. A lender will usually examine the development approval, quantity surveyor reports, builder contract, remaining cost to complete, end values, presales or sales strategy and experience of the development team.
This is specialist finance rather than easy finance. The facility must leave enough contingency for the project to reach a saleable or refinanceable point. If the feasibility only works on an optimistic end value or a perfect sales timeline, more debt may create a bigger problem rather than solve one.
Asset finance and leasing
Not every funding need should be secured against property. Asset finance can help self-employed borrowers acquire income-producing equipment, vehicles, plant, machinery or technology without tying up property equity. For a transport operator buying a ute or trailer, a contractor replacing machinery, or a medical practice purchasing equipment, the asset itself may provide much of the security.
Options can include chattel mortgages, finance leases and operating leases, depending on the asset, tax position and whether ownership at the end of the term matters. Asset finance is often better aligned with the useful life of the equipment than a short-term property-backed loan.
Lenders will still consider credit history, deposit, asset type and business trading evidence. However, a well-supported asset purchase can be easier to justify than an unsecured request for general working capital, especially where the equipment has a direct revenue role.
Bridging and mezzanine finance
Bridging finance suits a defined gap between two property events. Examples include buying a business premises before another property sells, settling a site while development funding is finalised, or refinancing a maturing loan before an expected sale. The strength of the proposal rests on the certainty and timing of the exit, not simply the borrower’s intention to sell.
Mezzanine finance sits behind senior debt and above equity in the capital stack. It is most relevant to experienced developers or commercial operators who need additional funds but do not want, or cannot obtain, more senior bank debt. Mezzanine funding can help preserve momentum on a project, but it is higher-risk capital and should be modelled carefully against sale proceeds, senior lender requirements and interest costs.
What strengthens a non-standard loan application
A lender does not need every document a bank asks for, but it does need enough evidence to understand the risk. The strongest applications are commercially coherent: the amount requested matches the use of funds, the security is clearly identified, and the exit is supported by facts rather than hope.
Prepare recent loan statements for the secured property, details of any existing mortgages or caveats, current rates notices, company or trust information and a concise explanation of the funding purpose. For business facilities, recent bank statements, BAS, management accounts, debtor information, purchase contracts or signed work contracts can add useful context. For developments, include the feasibility, approvals, build status, cost-to-complete estimate and sales evidence.
Be direct about impaired credit, ATO debt, arrears or previous lender issues. Surprises late in the process can delay settlement or reduce lender appetite. A clear explanation, backed by evidence that the issue is being managed, is far more useful than trying to minimise it.
Selecting finance that solves the actual problem
The lowest advertised rate is not always the lowest-cost outcome if it cannot settle when required or if the structure does not fit the transaction. Compare the total cost, term, repayment method, security ranking, valuation requirements, lender conditions and flexibility around early repayment. Most importantly, test the exit before accepting the funds.
No Doc Loans can assess the transaction and seek options across a panel of Australian private lending partners, helping borrowers compare structures where mainstream policy does not fit. The objective is not to force every scenario into private credit, but to find a facility that gives the business enough time and certainty to execute its next move.
When your income is complex, the right question is not whether a bank’s template can describe your business. It is whether the funding structure is secured sensibly, priced transparently and gives you a realistic path to the outcome you are working towards.

Leave A Comment