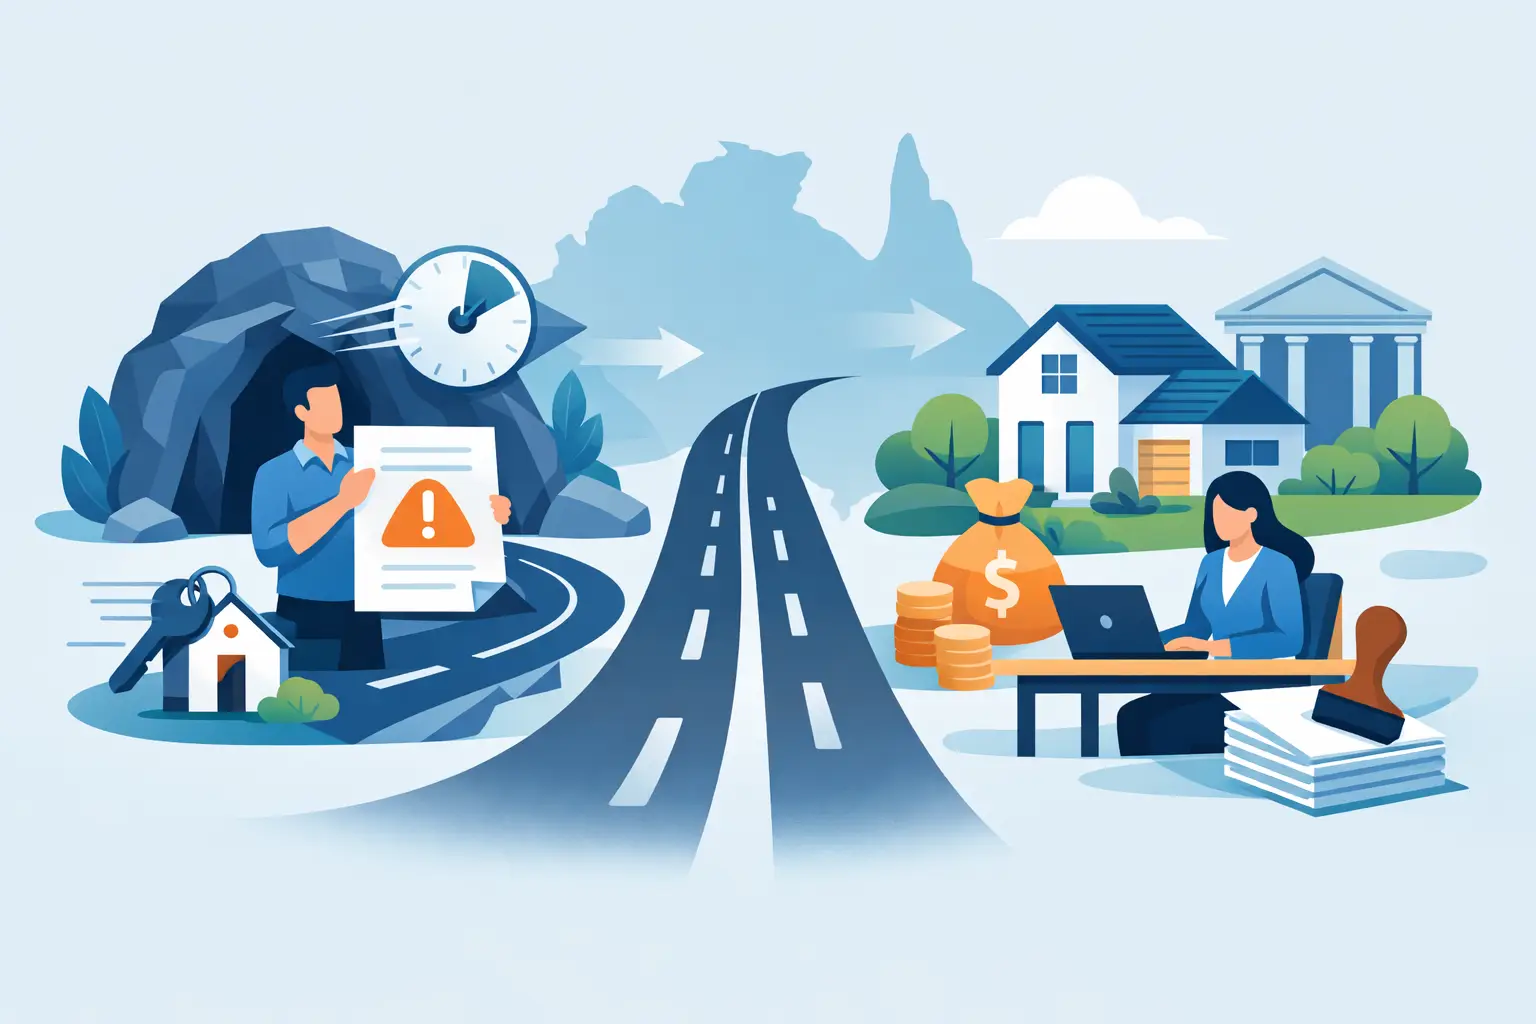
A settlement due this week, an ATO payment falling overdue, or a project that needs one final injection of capital can turn funding speed into the central commercial issue. Are caveats faster than mortgages? Often, yes. A caveat loan can usually be assessed, approved and settled more quickly than a loan requiring a registered mortgage – but it is not automatically the right or cheapest form of funding.
The real question is whether speed is worth the trade-off in term, pricing, loan size and security. For Australian business owners and developers, the right answer depends on why the funds are needed, how much equity is available, who already holds security over the property, and how quickly there is a clear exit.
Are caveats faster than mortgages in practice?
A caveat loan is commonly used as short-term, business-purpose funding secured by real property. Rather than registering a new mortgage on title, the lender lodges a caveat to protect its interest in the property while the loan is outstanding. That process can reduce documentation and settlement steps, particularly where the borrower needs funds urgently.
A mortgage is a more formal registered security interest. It generally involves a fuller legal process, more detailed due diligence and registration through the relevant state or territory land titles system. Where there is an existing first mortgage, the incoming lender may also need a discharge, refinance coordination, or consent and priority arrangements. Those steps are worthwhile for larger or longer-term facilities, but they can add time.
That does not mean every caveat loan settles overnight, or that every mortgage takes weeks. A clean title, a current valuation, straightforward company or trust documents, and responsive parties can speed up either structure. Conversely, a caveat loan can slow down if ownership is unclear, the property is held in a complex trust, there are caveats or writs already recorded on title, or the proposed lender cannot establish a valid caveatable interest.
As a practical guide, caveat funding is often considered when the borrower needs a decision within days and has a credible way to repay within a short period. Mortgage funding is usually better suited where the facility needs to run for months or years, the amount is larger, or pricing is a major consideration.
Why caveat loans can move quicker
The main advantage is a shorter path from application to settlement. Private lenders considering caveat security tend to focus on the available equity in the property, the purpose of the funds, the borrower’s exit strategy and any existing debt. For a business-purpose facility, this can be more commercially direct than a mainstream bank credit process centred on income verification, serviceability models and standard policy rules.
A lender may still require identification, rates notices, company searches, details of existing loans, bank statements, a valuation or desktop assessment, and legal advice. The difference is that the assessment can be tailored to the deal. A developer with retained stock, a business owner facing temporary cash-flow pressure, or a borrower with impaired credit may have a viable proposition even where a bank application is delayed or declined.
Caveat loans are particularly relevant where a borrower cannot wait for a refinance to complete. Examples include paying suppliers to preserve stock flow, meeting wages or tax obligations, securing equipment needed for a contract, settling an urgent purchase, or completing head works before a longer-term construction or development facility is available.
The speed comes from simplified security and a private-credit approach, not from skipping legal or commercial checks. Reputable lenders still need to understand the property, the debt position and the repayment plan. Fast funding should be decisive, not careless.
A caveat is not simply a faster mortgage
This distinction matters. A mortgage gives the lender a registered security interest and usually clearer enforcement rights. A caveat is a notice recorded on title claiming an interest in land. It can prevent dealings with the property, such as a sale or new mortgage, from proceeding without the caveator being notified or removed.
For this reason, caveat finance is generally short term and must be structured properly. A lender cannot simply lodge a caveat without a genuine legal basis. Borrowers should understand what they are signing, including the loan agreement, caveat authority, default interest, fees, extension options and the circumstances in which the lender may take recovery action.
If someone markets a caveat loan as easy money with no questions asked, treat that as a warning sign. The strongest private funding arrangements are transparent about security, costs and the exit strategy from day one.
When a mortgage may be the smarter choice
A first or second mortgage may take longer to establish, but it can provide a stronger platform for a meaningful funding requirement. This is often the case for a commercial-property acquisition, a development refinance, a substantial debt consolidation, or a facility intended to stay in place beyond a brief cash-flow gap.
Mortgage security can support larger loan amounts because the lender’s position is registered on title. It may also result in more competitive pricing and a longer loan term, especially where the borrower has a clear valuation, sufficient equity and an acceptable servicing or exit profile. A second mortgage can be a useful option where a first mortgage is already in place and the borrower needs to release additional equity without refinancing the senior debt.
For a developer, the timing decision often comes down to the next capital event. If a development is close to completion and a refinance, sales settlement or retained-stock facility is expected shortly, a caveat loan may bridge the immediate gap. If construction still has many months to run, or the project requires staged drawdowns, mortgage-backed development funding will usually be more appropriate.
The cost of delay must also be weighed against the cost of finance. Missing a discounted settlement, losing a supply contract or allowing a site to sit idle can cost far more than a short-term caveat loan. On the other hand, using expensive short-term funding for a long-term problem can create avoidable pressure when the maturity date arrives.
The questions to settle before choosing security
Before accepting either structure, a borrower should be able to answer four commercial questions clearly:
- How much is required, including interest, fees and a realistic contingency?
- What property is available as security, and what debt is already registered against it?
- What specific event will repay the loan, and when is it expected to occur?
- If that event is delayed, what is the backup exit?
An exit should be more than a general intention to sell or refinance. It may be a signed contract of sale, settled invoices, an approved refinance, a maturing asset sale, project settlements, or documented funds expected from another source. Lenders will look closely at this point because caveat finance is designed to be temporary.
It is also worth checking the existing loan documents before proceeding. Some first mortgage facilities restrict further borrowing or the registration of a caveat without consent. Ignoring those terms can trigger a default, even if there appears to be enough equity in the property.
Getting a fast answer without choosing the wrong loan
The quickest way to improve funding speed is to present the deal cleanly at the outset. Have the property address, ownership structure, current loan balances, purpose of funds, required settlement date and exit strategy ready. If a valuation, contract, council approval, quantity surveyor report or construction update is available, provide it early rather than waiting for a lender to request it.
A broker with access to a broad private-lender panel can then match the transaction to lenders that actually consider the proposed security and time frame. That is more effective than submitting the same urgent application to lenders whose policies do not fit the deal. No Doc Loans works with business-purpose borrowers to compare practical caveat, first mortgage and second mortgage options based on the asset, urgency and proposed exit.
Fast finance works best when it buys time for a defined commercial outcome. If a caveat loan gets a viable project moving, protects a valuable opportunity or bridges a short and well-documented gap, its speed can be highly valuable. If the funding need is larger, longer or dependent on an uncertain exit, taking the extra time to establish mortgage security may protect both the project and the borrower’s equity.

Leave A Comment