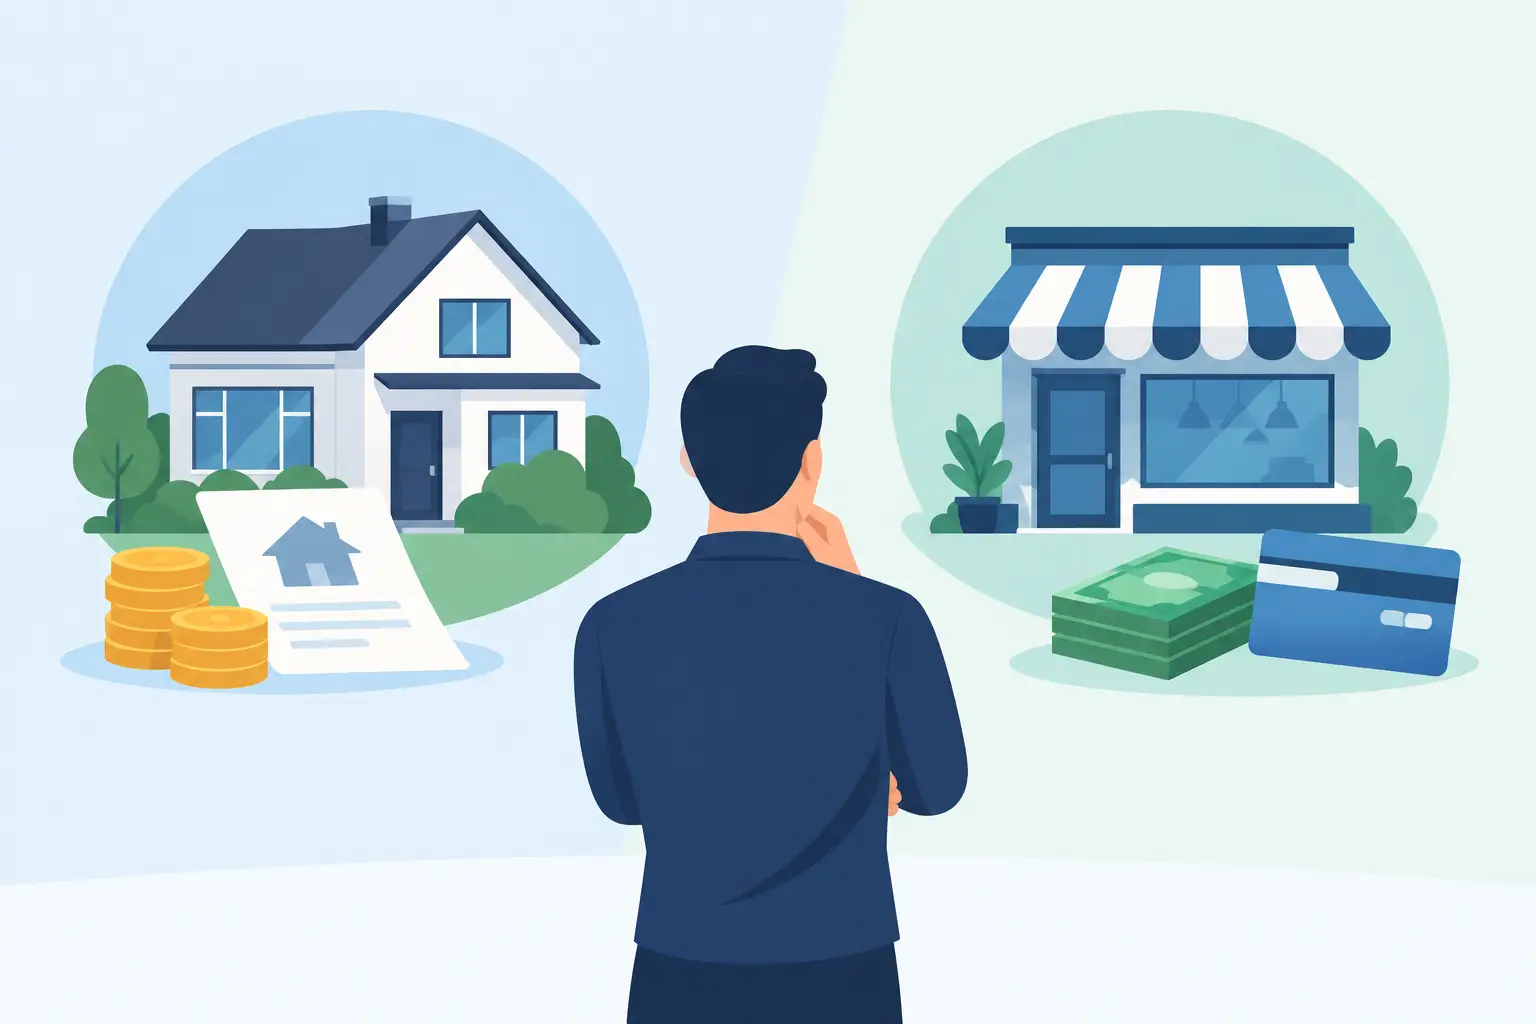
A supplier wants payment before releasing stock. Your BAS bill is due. Or a development site needs head works completed before the next stage can begin. When cash is tied up in property, stock or receivables, the funding structure matters as much as the amount. The property loan vs business overdraft decision is not simply about which facility is easier to obtain. It is about matching the debt to the asset, timeframe and commercial outcome you need.
For Australian business owners and developers, an overdraft can be useful for day-to-day fluctuations. A property-backed business loan can be more suitable where a defined capital requirement, property equity or a time-sensitive opportunity is involved. Choosing the wrong one can leave a business paying for flexibility it does not need, or worse, relying on short-term cash flow for a long-term funding need.
Property loan vs business overdraft: the core difference
A business overdraft is a revolving facility attached to a business transaction account. It lets the business draw up to an approved limit, repay funds as cash comes in, then redraw when needed. Interest is generally charged only on the amount used, rather than the full approved limit. It is designed for working-capital movements, such as bridging the gap between paying suppliers and receiving customer payments.
A property loan for business purposes is a lump-sum facility secured by real estate. The security may be a first mortgage, second mortgage or caveat over residential, commercial or industrial property. Depending on the lender and structure, the funds may be used for business expansion, tax liabilities, stock purchases, debt consolidation, site acquisition, construction completion or an urgent commercial settlement.
The central distinction is simple: an overdraft provides a reusable cash-flow buffer, while a property loan releases a defined amount of capital against available property equity. Both can support a business, but they solve different problems.
When a business overdraft makes commercial sense
An overdraft can suit an established business with predictable trading cycles and regular receipts. A wholesaler that buys inventory ahead of a seasonal sales period, for example, may use an overdraft for several weeks and clear it as invoices are paid. A professional services firm may use one to cover wages while waiting for larger client accounts to settle.
Because the facility revolves, it can be efficient where the shortfall changes from week to week. The business does not need to apply for a new loan every time it needs a modest injection of cash. This flexibility is valuable when the timing of payments is uncertain but the underlying revenue is reliable.
There are limits to that flexibility. Overdrafts are commonly reviewed periodically and may be repayable on demand, subject to the facility terms. A lender will often assess business financials, account conduct, serviceability, trading history and director credit profiles closely. New businesses, companies with impaired credit, trusts with complex income, or businesses recovering from a difficult period may find bank overdraft approval challenging.
An overdraft is also not a good substitute for a large, one-off capital requirement. Using a revolving facility to fund a property deposit, clear a tax debt, complete a build or purchase major equipment can create pressure if the facility needs to be reduced before the project generates its expected return.
When a property-backed business loan is the stronger option
A property loan is often more practical when the business needs a material amount of money for a known purpose and there is equity in real estate to support the borrowing. Private lenders generally place significant weight on the quality and value of the security, the loan-to-value ratio, the exit strategy and the commercial rationale for the loan.
Consider a developer holding retained stock that has not yet sold. The project may be fundamentally sound, but delays in settlement or a lack of current pre-sales can make mainstream bank funding difficult. A short-term second mortgage or caveat loan may release enough equity to finish external works, pay contractors or meet holding costs while sales are completed.
The same principle can apply to an operating business. A company may own a warehouse, an investor may hold an unencumbered residential property, or a director may have equity in a commercial asset. Rather than waiting through a lengthy bank process for an overdraft that may not meet the required limit, a property-backed facility can provide a clear funding amount and a defined term.
Private property loans can also be structured around non-standard circumstances. This may include recent credit issues, an incomplete development, residual stock, a short settlement deadline or business income that does not fit a standard bank assessment model. That does not mean the loan is automatic. The security, valuation, existing debt position and credible exit still need to stack up.
Compare cost, speed and certainty – not just interest rate
The headline interest rate is only one part of the comparison. An overdraft may appear cheaper on paper, particularly when it is only lightly used. However, there can be establishment fees, line fees, annual review requirements and charges associated with excess or unauthorised drawings. Its real value lies in ongoing access to cash, not necessarily in funding a major transaction.
A private property loan may have a higher rate and upfront costs than a bank overdraft, particularly where it is short term, second mortgage security or a caveat structure. Those costs need to be weighed against what the funding enables. Missing a discounted stock purchase, losing a site under contract, failing to complete a project stage or incurring penalties on an overdue obligation can cost far more than the difference in finance pricing.
Speed is another practical consideration. Overdraft applications through a mainstream lender can require full financials, cash-flow forecasts, tax returns, management accounts and a detailed credit assessment. Where the bank has all information available and the business is trading strongly, that process may work well.
Where time is tight, property-backed private finance can be assessed with greater emphasis on security and exit. A lender may still request company and trust documents, rates notices, mortgage statements, a valuation and details of the intended use of funds. Yet the structure can be more responsive for borrowers who need to settle, refinance or act on a commercial opportunity within a short timeframe.
The security question: what are you putting at risk?
An unsecured overdraft, where available, does not usually require a registered mortgage over property. In practice, many business overdrafts involve director guarantees, general security arrangements, property support or other security depending on the borrower and lender. Read the documents carefully rather than assuming an overdraft carries no personal exposure.
A property loan is explicitly secured against real estate. If repayments or the agreed exit are not met, the lender has enforcement rights under its security documents. For a first mortgage, the lender ranks ahead of later secured parties. For a second mortgage or caveat loan, the lender’s position is behind the first mortgage holder, which usually affects pricing, maximum loan amount and conditions.
This is why the exit strategy deserves serious attention. The exit could be property sale, refinance to a mainstream lender, sale of retained stock, settlement of receivables or incoming project proceeds. It should be realistic, timed conservatively and supported by evidence where possible. Borrowing against property to solve a short-term problem only works when there is a credible path to repay the debt.
Match the facility to the timeframe
A useful rule is to avoid funding a long-term need with a short-term cash-flow facility. If you need to cover a few weeks of timing mismatch between invoices and expenses, an overdraft may be appropriate. If you need capital to complete a development, consolidate multiple debts, acquire a business asset or preserve a settlement, a property loan with a planned term is often easier to manage.
There are exceptions. A profitable business with strong bank conduct may use an overdraft for a substantial working-capital cycle. Conversely, a small shortfall may still justify a caveat loan if the urgency is high and equity is readily available. The right structure depends on how much is needed, how quickly it is required, what security is available and exactly how the facility will be repaid.
A practical way to assess your options
Before applying, define the purpose in one sentence. For example: “We need $350,000 to complete civil works and release 12 contracted settlements within four months.” That clarity helps determine whether the request is a revolving working-capital need or a defined project facility.
Then map the cash flow. Identify when the funds are required, when money is expected back into the business and what happens if that date slips. Finally, review available security and existing debt. A lender will need to understand whether there is sufficient equity after first mortgages and other claims are taken into account.
No Doc Loans can assess property-backed business funding requirements across a panel of private lenders, including first mortgages, second mortgages and caveat loans. For borrowers facing bank delays or a non-standard scenario, comparing structure, term, security and exit can be more useful than pursuing a single product in isolation.
The best funding decision is the one that gives your business enough capital to act, enough time to execute the plan and a repayment pathway that remains workable if conditions take longer than expected.



Leave A Comment