A company acting as trustee can own valuable property, operate a business or hold a development site, but it does not automatically make borrowing straightforward. Corporate trustee borrowing requirements turn on the trust deed, the trustee company’s authority, the proposed security and the people standing behind the transaction. Get one of those wrong and a lender may decline the deal, delay settlement or require a restructure before funds can be released.
For Australian business owners and developers, the practical question is usually not whether a trust can borrow. It is whether the proposed loan can be documented cleanly, secured properly and settled in time to acquire a site, finish construction, refinance a maturing facility or release working capital.
What a lender needs from a corporate trustee
A corporate trustee is a company that holds assets and enters transactions for a trust. The trustee is the legal borrower and signatory, but it acts in its capacity as trustee rather than for its own benefit. For that reason, lenders need to establish both that the company exists and that it has a right to borrow for the trust.
The starting point is the trust deed. It should give the trustee a clear power to borrow, grant mortgages or other security, provide indemnities and deal with the relevant trust assets. A well-drafted deed usually covers these powers, but lenders will still review the wording. Older deeds, deeds prepared for a narrow family purpose, or documents that have been varied several times can create uncertainty.
The trustee company also needs authority under its constitution or the replaceable rules, together with properly executed director resolutions. If the company has more than one director, all required directors generally need to approve and sign. Where a corporate beneficiary, unit holder or appointor has consent rights under the deed, those approvals may also be needed.
This is not paperwork for paperwork’s sake. It protects the lender’s ability to enforce its security against trust assets if the loan defaults.
Corporate trustee borrowing requirements for security
Most private lenders focus first on the quality and value of the proposed security. For a property-backed business-purpose loan, this may be a first mortgage over commercial, industrial, residential investment or development property held by the trust. Depending on the deal, a second mortgage, caveat, general security agreement or a combination of securities may be considered.
The security must be owned by the correct entity. If the contract, title, existing mortgage and proposed borrower do not align, the deal needs careful attention. A common example is a property acquired in a company’s own name when it was intended to be held by the company as trustee. Another is a development site held by one trust while the operating business seeking working capital sits in another.
A lender will normally assess the current value, existing debt, available equity and the likely saleability of the asset. For development funding, it may also examine planning status, head works, construction progress, quantity surveyor reports, builder arrangements and the end value. A lack of pre-sales may rule out a bank facility, but it does not necessarily rule out private funding if the leverage, exit and asset position are sensible.
The loan purpose matters as well. Private business-purpose finance may be suitable for acquisitions, construction completion, tax liabilities, stock purchases, equipment, debt consolidation or short-term cash flow. If the primary purpose is personal, domestic or household, a different regulatory and credit assessment pathway may apply.
The documents that usually decide the pace of approval
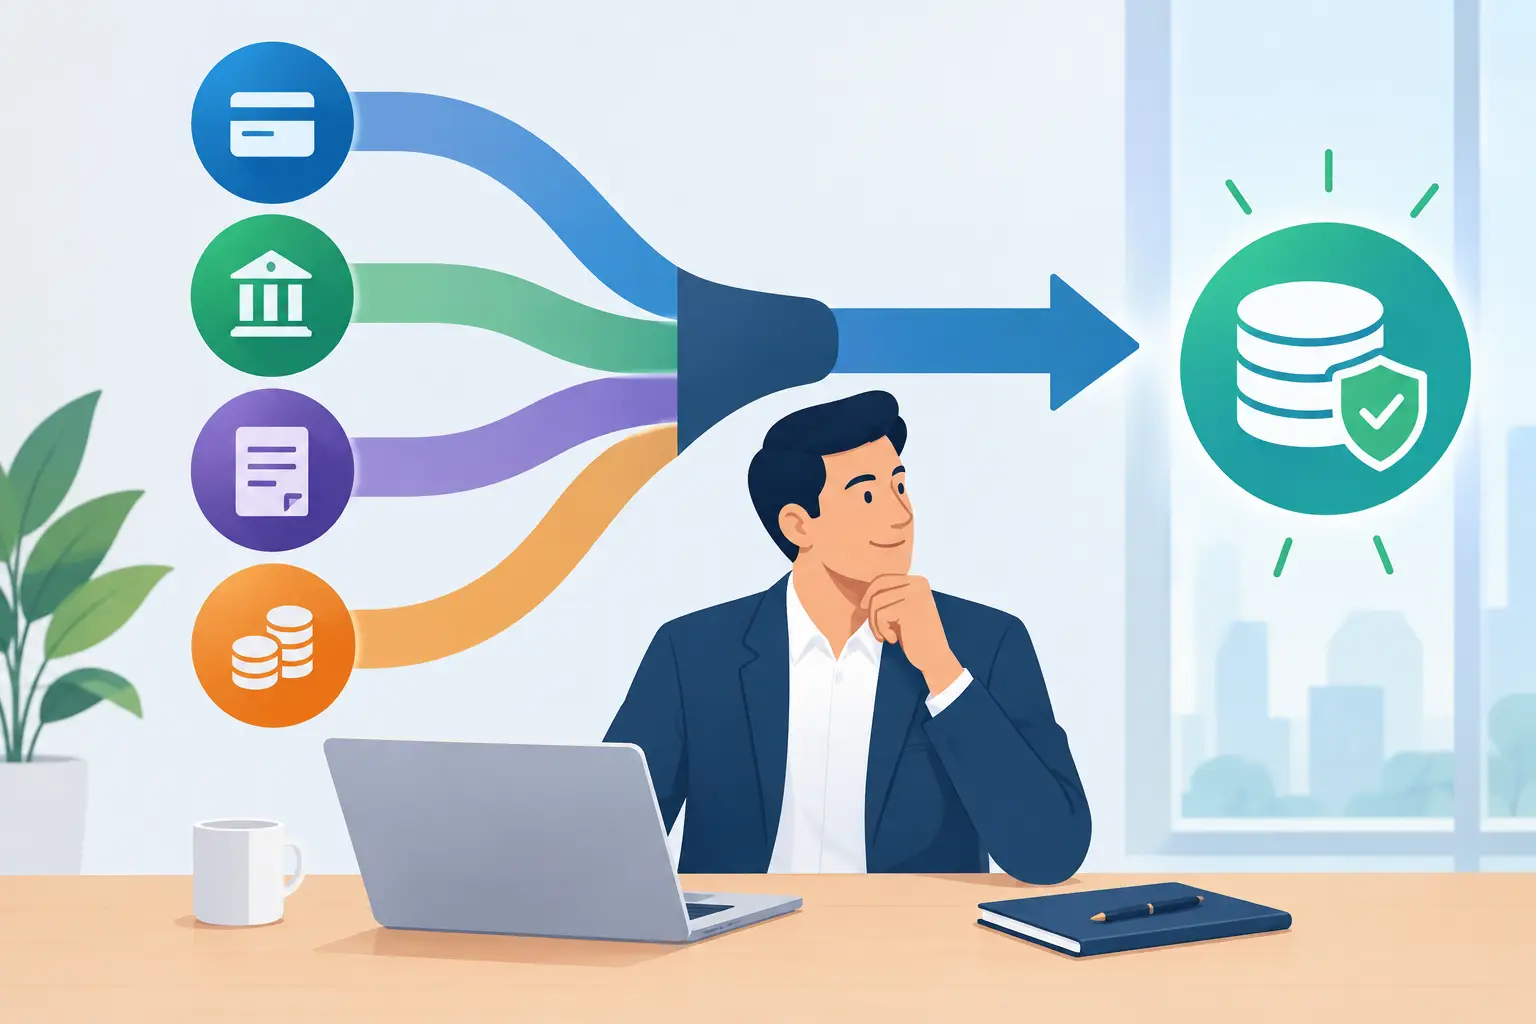
A clean document pack helps move a corporate trustee loan from enquiry to terms quickly. Requirements differ by lender and facility size, but most applications call for the following:
- The executed trust deed, plus every deed of variation, change of trustee deed and relevant appointment document.
- ASIC company records for the corporate trustee, including directors, shareholders and company details.
- Current identification and beneficial ownership information for directors, beneficiaries, unit holders and controllers.
- Property documents, such as title searches, rates notices, lease details, existing loan statements, valuations and contracts of sale where relevant.
- Financial information that supports the exit strategy, including BAS, bank statements, rental income, management accounts, tax returns or development feasibility figures.
Not every private lender needs two years of financials. In asset-backed lending, the property security and exit can carry more weight than a conventional serviceability model. Still, a lender will want a credible explanation of how the facility will be repaid. That may be a property sale, refinance on completion, retained-stock sale, business cash flow or settlement of an identified contract.
If documents are missing, do not assume the transaction is finished. A practical lender may accept alternative evidence while formal documents are obtained, particularly where there is a strong first-mortgage position and a clear exit. The limits of that flexibility depend on the risk profile, loan-to-value ratio and urgency.
Guarantees, indemnities and who is actually liable
The trustee has a right to be indemnified from trust assets for liabilities properly incurred in performing its role. Lenders rely heavily on that right. However, the right can be limited if the trustee acted outside the trust deed, breached its duties or lost its entitlement under the trust terms.
That is why personal guarantees are common. Directors, key beneficiaries or unit holders may be asked to guarantee the loan, especially where the trust is closely held or the loan is being used for an operating business. A guarantee gives the lender another recovery path if trust assets are insufficient or an issue arises with the trustee’s indemnity.
Guarantees are not automatic in every transaction. A strong, low-leverage property deal with substantial rental income may be assessed differently from a higher-leverage development facility or a caveat loan required within days. The proposed guarantors’ position, the security value and the exit all influence the final structure.
Borrowers should also understand capacity. Loan documents should identify the company as borrowing “as trustee for” the named trust. If it signs in its personal capacity as well, exposure can extend beyond the trust assets. Legal advice is particularly worthwhile where there are multiple trusts, related entities, incoming investors or cross-collateralised properties.
Common issues that stop a trust loan at the last minute
The most avoidable problem is an incomplete trust chain. A lender may receive the original deed but not the later deed that appointed the current corporate trustee. Without evidence of that change, it cannot be certain who has authority to mortgage the property.
Another issue is a trust deed that prohibits or restricts borrowing without consent. This can often be addressed by obtaining the required consent or varying the deed, but it should be identified before the settlement date becomes critical.
Existing financiers can also complicate matters. Their mortgage may contain priority, refinance or release conditions. A second mortgage or caveat lender needs to know the exact first-mortgage balance and whether the senior lender will permit the proposed transaction. For a refinance, payout figures and discharge timing need to be managed early.
Finally, do not overlook trust type. Discretionary trusts, unit trusts, trading trusts and bare trusts each have different mechanics. Self-managed super fund borrowing is subject to specialised legal and structural rules, including limited recourse arrangements, and should not be treated like an ordinary corporate trustee loan.
Matching the facility to the deal
Bank lending can work well where the trust has clean financials, ample time and a straightforward property or business profile. The challenge is that a bank process may not suit an incomplete development, a credit-impaired director, a tax arrears position, residual stock or a time-sensitive settlement.
Private lending is often more useful when the transaction needs a commercially reasoned structure rather than a standard credit box. A short-term first mortgage may fund an acquisition while a longer-term refinance is arranged. A second mortgage may release equity without disturbing an existing senior facility. A caveat loan may bridge an urgent obligation, provided the security, repayment plan and costs make commercial sense.
No Doc Loans can assess the trust structure, property security and funding objective, then seek suitable terms from a panel of private lenders. The aim is not to force every trust into the same product, but to identify what can be documented and settled with a workable exit.
Before committing to a contract or promising a settlement date, gather the full trust history and confirm who can sign. That small piece of preparation can be the difference between a funding conversation that stalls and one that gets your project moving.

Leave A Comment