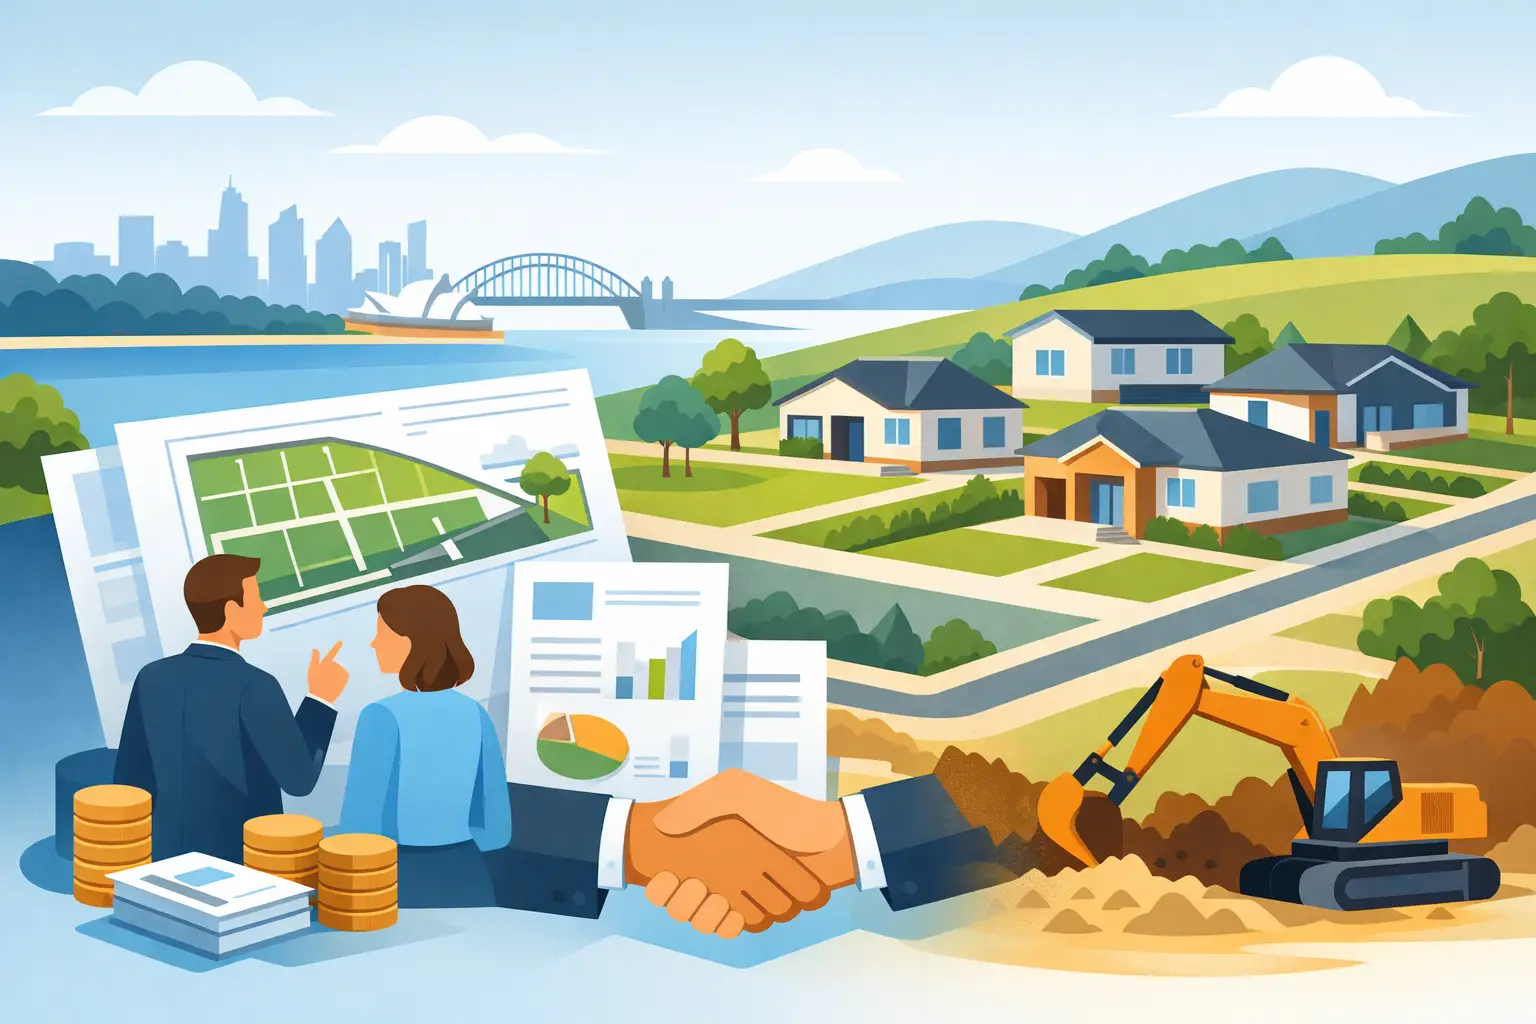
A stalled subdivision rarely stops because the project has no value. More often, it stops because the last funding requirement arrives at the worst possible time: civil works need paying, titles are not yet registered, and the bank wants more pre-sales or a cleaner balance sheet. This subdivision funding case study shows how private finance can provide a practical path through that gap when the underlying security and exit are clear.
The scenario is illustrative, but it reflects the funding pressures regularly faced by Australian developers completing small-to-medium residential estates.
The project: value tied up in unregistered lots
A NSW developer had acquired a site approved for a 24-lot residential subdivision in a growth corridor outside Sydney. The development approval was in place, the bulk earthworks and drainage were complete, and civil contractors had started roads, kerbing, sewer connections and electrical works.
The original senior lender had funded the land acquisition and early works. Its facility was approaching expiry, however, and the lender was unwilling to extend the loan without stronger pre-sales. Market conditions had softened during the construction period. Buyers were still enquiring, but several purchasers wanted registered titles before committing to unconditional contracts.
That left the developer with a familiar circular problem. It needed money to complete the head works and obtain registration. Yet without registration, it could not settle land sales and reduce debt in the way its bank required.
The immediate requirement was $2.15 million. Approximately $1.55 million was needed to clear outstanding civil invoices and finish the remaining works. The balance was required for interest, statutory costs, contingency and a controlled working-capital buffer while titles progressed through registration.
Why conventional bank funding was not the right fit
The developer had equity in the project, but equity alone does not guarantee a timely bank approval. The bank needed a full re-assessment of current valuation, project feasibility, borrower servicing, pre-sales and construction status. The process could take weeks, and the facility expiry was less than a month away.
There were other complications. The developer had two residual lots in an earlier project, which affected the group’s reported debt position. Its director had also used personal funds to manage an unrelated business interruption during the previous year. Neither issue necessarily made the project unfinanceable, but both created additional questions under mainstream credit policy.
The key distinction was timing. The developer was not seeking speculative land funding with no defined use of funds. It needed a short-term completion facility against a partly completed project with approvals, physical progress, a clear cost-to-complete and an identifiable sales exit.
The proposed subdivision funding structure
A private lender was introduced through a broker with access to multiple private-credit partners. The lender assessed the project primarily on its as-is security value, realistic gross realisation value, remaining works, borrower experience and the credibility of the exit strategy.
The proposed facility was structured as a first mortgage refinance and construction-completion loan. It refinanced the existing senior debt and released the additional funds required to complete the estate. The total facility was $6.4 million, inclusive of the existing debt payout, the $2.15 million completion requirement, interest reserves and lender costs.
Rather than advancing all funds at settlement, the lender funded the construction component through staged drawdowns. This mattered for both parties. The developer had access to capital when invoices fell due, while the lender could monitor progress through quantity surveyor updates, civil engineer certification and evidence of completed works.
The facility included a 12-month term with an extension option, subject to agreed conditions. Its proposed exits were lot settlements after registration, with the capacity to refinance any unsold residual stock into a longer-term facility if sales took longer than forecast.
Security and lender protections
The lender took a registered first mortgage over the subdivision site. It also required standard supporting security from the borrowing entity and directors, together with assignment of relevant project insurances and material contracts.
A detailed cost-to-complete schedule was critical. Private lenders can be more flexible than banks, but they still need confidence that the requested funds will get the project to a value-creating milestone. In this case, that milestone was practical completion followed by title registration.
The lender also set a minimum interest reserve and retained a contingency allocation. This reduced the risk that a modest delay in council sign-off, utility connection or Land Registry Services processing would leave the developer short of funds.
What changed once funding settled
Settlement allowed the developer to pay overdue civil contractors and recommence the work programme immediately. The project team focused on completing the road surface, final drainage, landscaping, street lighting and utility connections needed for council and certifier sign-off.
The staged funding arrangement improved discipline around the remaining budget. Each drawdown was tied to a defined work package, supported by invoices and progress evidence. That did not remove the developer’s responsibility to manage contractors, but it gave all parties a clearer view of cash flow and project status.
Registration was achieved several months later. By then, the developer had converted several buyer enquiries into signed contracts and was able to begin settling lots. Proceeds were applied to reduce the private facility progressively, in line with the agreed release price schedule.
The release prices were especially important. A lender will usually want each lot sale to reduce its exposure by a sensible amount, rather than allowing the strongest lots to be sold too cheaply while debt remains secured against less marketable stock. Getting those release terms right at the start preserved the developer’s ability to trade through the project while maintaining lender confidence.
The trade-offs in using private subdivision finance
Private funding is not automatically the cheapest source of capital. Rates, establishment fees and legal costs can be higher than a conventional bank facility, particularly where the lender is taking construction, settlement or market-risk exposure.
For this developer, the relevant comparison was not simply private funding versus a bank rate. It was private funding versus the cost of missing contractor payments, losing momentum on site, allowing the senior loan to expire and delaying title registration. A lower-priced facility that cannot settle in time may be more expensive in commercial terms.
There was also no guarantee that every lender would support the transaction. Projects with a large funding gap, weak approvals, an unclear cost-to-complete, unresolved planning issues or no viable sales and refinance exit can still be declined. Flexible credit is not a substitute for a viable development plan.
What made this case fundable
This transaction worked because several fundamentals aligned. The site had development approval, the works were well advanced, the developer could demonstrate experience, and the requested funds were specifically allocated to completing identifiable project milestones.
The valuation evidence also supported the lender’s position. The facility was sized with reference to conservative as-is and end-value metrics, not just the developer’s preferred selling prices. A realistic assessment of likely sales rates and residual stock was necessary, particularly in a changing market.
Finally, the borrower did not wait until the last possible day to seek options. Although the senior lender’s expiry created pressure, the developer had enough time to provide plans, approvals, valuations, construction contracts, a feasibility study, debt statements and a detailed use-of-funds schedule. That preparation helped lenders move from an initial indication to a credit decision without unnecessary delays.
Preparing a subdivision funding enquiry
Developers seeking funding for a subdivision should expect lenders to look beyond the headline site value. They will want to understand where the project sits today, what remains to be done, how much it will cost and exactly how the debt will be repaid.
A strong funding submission usually includes the development approval, plans, current valuation, project feasibility, quantity surveyor report where available, construction or civil-work contracts, a cost-to-complete schedule, existing loan payout figures and evidence of pre-sales or buyer interest. If there are delays, disputes or variations, explain them early. Credit concerns are easier to manage when they are identified and quantified rather than discovered late in due diligence.
For a project with genuine equity and a defined completion path, private development finance can turn a registration delay into a manageable funding exercise. The right facility is not simply the fastest quote – it is the one that gives the project enough time, enough contingency and a realistic exit to get lots sold and capital moving again.

Leave A Comment